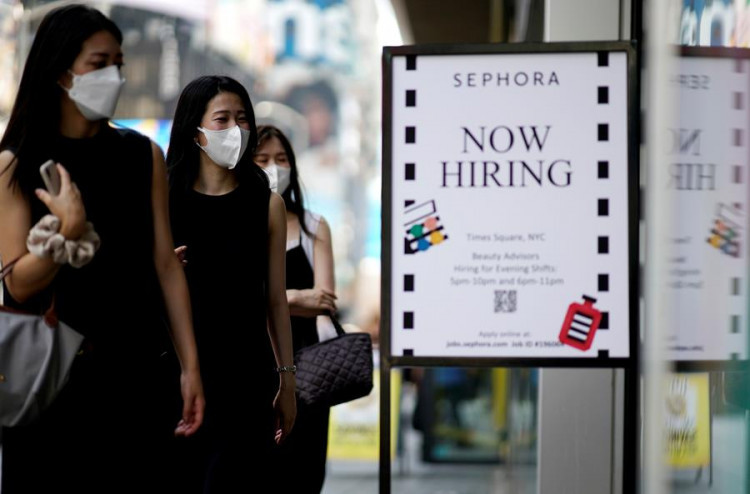
The U.S. economy added 29,000 jobs in September, falling well short of forecasts as unemployment rose to 4.2% and downward revisions erased 60,000 jobs from previous months, according to Bureau of Labor Statistics figures released Friday.
The report showed a weaker labor market heading into November's midterm elections. Economists surveyed by Dow Jones had expected 84,000 additional jobs and an unemployment rate unchanged at 4.1%, while wage growth also came in below expectations.
September's slowdown followed a less robust summer than initially reported. August's payroll gain was reduced to 133,000 from 162,000, and July's previously reported increase of 21,000 became a loss of 10,000, leaving employers with considerably less hiring momentum than earlier estimates suggested.
Workers' paychecks grew more slowly as well. Average hourly earnings increased 0.1% from August and 3% from a year earlier, below the 3.1% annual increase economists had anticipated.
Health care, construction and manufacturing led September's employment gains, while financial activities lost positions. Payroll growth has fluctuated substantially this year, even as the unemployment rate has moved within a relatively narrow range.
The weaker federal report contrasted with an upbeat reading from payroll processor ADP earlier in the week. ADP estimated that private employers added 90,000 jobs in September, exceeding the 68,000 forecast in a separate Dow Jones survey.
"After a three-month slowdown, job creation rebounded and pay growth remained solid," ADP Chief Economist Nela Richardson said. ADP's private-sector estimate and the BLS total nonfarm figure measure different employment universes and should not be treated as interchangeable.
In ADP's breakdown, education and health services added 55,000 positions, while leisure and hospitality gained 22,000. Financial activities shed 16,000 jobs and professional and business services lost 11,000, showing that the stronger overall reading still included pockets of weakness.
Other indicators suggested that disappointing hiring had not been accompanied by a surge in announced layoffs. U.S.-based employers announced 43,281 job cuts in September, down 18% from August and 20% from a year earlier, according to Challenger, Gray & Christmas.
That was the lowest September total since 2022. Announced cuts for the first nine months reached 573,195, a decline of 39% from the same period in 2025.
Employees nevertheless reported growing unease about their employers' prospects. Glassdoor's Employee Confidence Index reached a record low in September, with 42.9% of workers submitting reviews expressing a positive six-month outlook, down from a revised 44.5% in August.
Glassdoor Chief Economist Daniel Zhao attributed the deterioration to concerns about job security, economic uncertainty and inflation. References to artificial intelligence in employee reviews rose 164% from a year earlier, while mentions of uncertainty increased 84% and layoffs 13%.
Friday's release is the final monthly employment report before the midterms, arriving as President Donald Trump and Republicans face pressure over economic conditions. Higher borrowing costs add another burden: the average 30-year fixed mortgage rate reached as high as 7.6% this week as long-term Treasury yields climbed.